Before a big trip there’s a moment most of us know well. The flights are booked, the room’s paid for, the insurance is sorted. Then someone asks, “Have we got enough spending money?”
It’s a different question from the budget. The budget is the trip on paper. Spending money is what lets you actually enjoy it: the boat trip you hadn’t planned, the long lunch that turns into an afternoon, the thing in a market window you know you’ll regret leaving behind. Spending in retirement works in exactly the same way. You can have a plan that adds up perfectly and still find you can’t bring yourself to use it.
So this piece isn’t about whether you’ve saved enough. It’s about whether you feel free to spend what you have.
You can have a plan that adds up perfectly and still find you can’t bring yourself to use it.
Life costs what it costs
Nobody plans a holiday by asking what the average holiday costs. You start with where you want to go and what you want to do there, and the price follows. A week walking in the Lakes and three weeks in Canada are different trips with different price tags. Neither is wrong.
Retirement gets planned the other way round surprisingly often. People start with a number they’ve heard, a rule of thumb, or what a colleague said they needed, and then try to fit a life inside it. (I wrote about that borrowing habit back in August, and it’s remarkably catching.) Or they work on what they are used to earning and spending now rather than the ideal future.
The more useful starting point is the honest one. What does the life you actually want cost? Not the brochure version, and not the bare minimum either. Life costs what it costs. Some years will be heavier than others: a big trip, a new car, helping someone you love through a tricky patch. That isn’t the plan going wrong. That’s the plan doing its job.
Once you know that figure, the question changes. It stops being “Will I have enough?” and becomes “Does what I have fit the life I want?” That’s a far calmer question to sit with.
Some years will be heavier than others. That isn’t the plan going wrong. That’s the plan doing its job.
The top drawer
Whenever Hazel and I travel, we take enough money for what we know we’ll need, either in local currency or on a prepaid travel card. Then we add a bit more for the fun. We know something will come up that we haven’t planned, something we’ll want to do or buy, and we’d rather say yes than do sums in our heads.
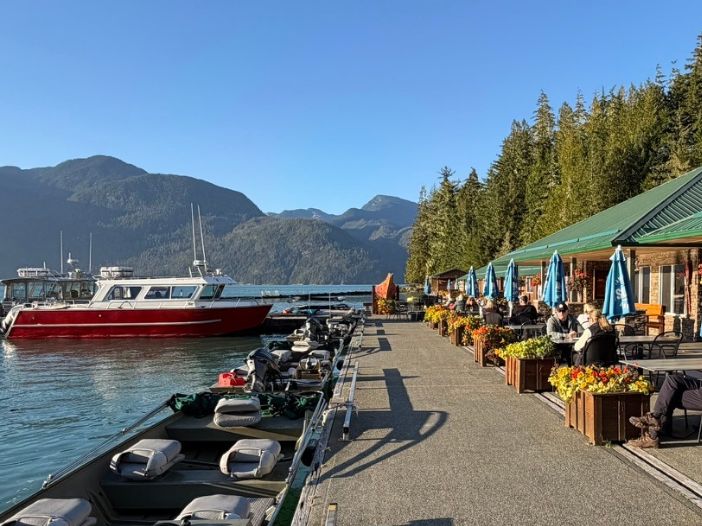
Most of the time that fun money gets used and we come home with nothing left. But on our recent trip to Vancouver, we were nearly at the end and there was still some in our pocket. We could have brought it home, and that would have been fine. Instead we gave ourselves an extra treat. We booked a couple of dinners out, nicer than we’d usually choose, with great views and lovely food.
It was a wonderful way to finish the holiday. And what made it better was knowing the money was already there, set aside for exactly that.
Bringing your spending money home unspent isn’t a failure. But it isn’t a prize either.
Bringing your spending money home unspent isn’t a failure. But it isn’t a prize either.
In retirement I call this the top drawer. It’s a comfortable cash reserve, kept somewhere you can reach easily, sitting apart from your longer-term money. How much goes in it is personal, and it’s worth working out properly as part of your plan rather than guessing. But its job is the same for everyone. When the boiler goes, the car needs replacing or a last-minute trip comes up, you don’t feel the floor shift underneath you.
Strange as it sounds, the top drawer isn’t really about emergencies. It’s about permission. When you know the cushion is there, you stop treating every bit of spending as a small threat to your future. You can book the dinner with the view.
The person who did everything right
Here’s a pattern I see more often than you might expect. Someone works for thirty or forty years, saves carefully, makes sensible decisions and arrives at retirement in good shape. And then they can’t spend it.
I think of a couple I worked with, John and Jill (not their real names). Both retired, with secure pension income and around £75,000 put by. Every year they had one two-week holiday abroad, budgeted at about £4,000.
They wanted more. A longer trip, or a second one. They could clearly afford it, but it meant dipping into their savings rather than living on income alone, and that felt like crossing a line.
It took a few conversations and some financial modelling before they moved. First to three weeks. Then a second, more luxurious trip later in the year. A couple of years on, they were spending around £3,000 a year more and still had more than enough. The money hadn’t changed. Their permission to use it had.
The money hadn’t changed. Their permission to use it had.
Often it goes deeper than the numbers. Many of the people I work with are carrying what they saw in their parents, whether that was money always being tight or a comfortable retirement that slowly got smaller. Habit plays its part too. For decades, saving was the right thing to do. Every pound put away felt like a small win. Then retirement arrives and asks you to flip the habit of a lifetime overnight, to start drawing on the thing you’ve spent your working life building up. Nobody hands you a new set of instincts at the leaving do.
So the money sits there. The trip gets put off until next year. The kitchen that needed doing stays as it is. Life gets lived carefully, a little smaller than it needs to be, just in case.
This isn’t only my impression. Research from the Institute for Fiscal Studies found that, on average, people drew down only around a third of their financial wealth between the ages of 70 and 90. Even among the better-off, most of it stayed put. Some of that is a deliberate choice to pass money on, and that’s a perfectly good choice when it’s a choice. But for plenty of people it’s simply caution that never got switched off.
If that sounds like you, it isn’t a character flaw. It’s the missing deadline again, in a different coat. A holiday tells you when the spending starts: you land, and that’s that. Retirement never does. Nobody confirms it’s safe to begin, so “one day” just keeps moving.
Three questions worth asking
Last month I wrote about when do you go? and choosing your own date. This is the other half of the same decision. Knowing when you’ll go is one thing. Knowing you’ll let yourself enjoy it once you’re there is another. If you’d like to sit with this properly, three questions help:
- Do I know what my life actually costs? The version I want, not the minimum.
- Is there money within reach that lets me say yes without worrying?
- What am I holding back on, and is the reason still true?
If you can answer the first two with confidence, the third often takes care of itself. That’s where a proper plan earns its keep. Not as a spreadsheet that proves you’re safe, but as the thing that shows you what’s genuinely possible, so spending in retirement starts to feel like the point rather than the risk.
Very few people come home from a holiday wishing they’d spent less on the boat trip. Your plan should give you that same freedom.
So, have you packed enough spending money? And just as importantly, are you letting yourself spend it?
If this has struck a chord, you might enjoy my fortnightly newsletter. There’s one for people approaching retirement and one for those already there, and you can choose the one that fits you. No pressure, just something useful in your inbox every other week.
This piece is part of a series that starts with the two-week holiday that lasts thirty years.

