Back in June, an email arrived telling us the balance was due on our trip to Vancouver Island. Nothing about it was a surprise. We’d booked it months earlier and we knew roughly when the money was needed. But an email like that does something a booking confirmation never quite manages. It puts a date in front of you and starts a clock running.
Getting ready to retire works nothing like that. There’s no email, no balance, no date that holds still. And that difference explains more about why people arrive at retirement underprepared than any amount of financial discipline ever will.
Twelve weeks out, and then ordinary life
The balance fell due twelve weeks before we travel. At the time, twelve weeks felt like plenty.
Then June became July, and July became August, and I couldn’t give you a proper account of where that time went. Client work happened. The newsletter went out. Ordinary weeks, the usual small admin of a life. The trip sat in the diary, paid for and settled, and I did almost nothing about it.
Which felt entirely fine, because the big thing was done. The money had gone. We were committed.
Paying the balance isn’t the same as being ready to go.
What the last four weeks have actually looked like
It’s only in the past month that the trip has started to feel real, and that’s when the work began.
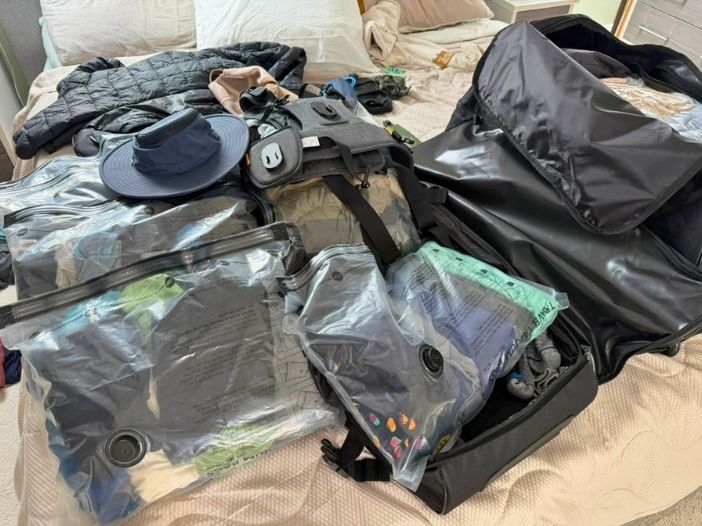
Three weeks, several locations, a busy itinerary. We’ve been going back over what we booked and why, because you forget. The order of things, the transfers, the days with something fixed in them and the days without. Then the packing, which for a trip like this isn’t a small job. I’ve been through my camera gear more than once: bodies, lenses, batteries, cards, the long lens I’ll want for bears and whales and will resent carrying the rest of the time. Hazel has been working out how to compress three weeks of clothing across multiple locations without either of us hauling more than we can lift.
A combined effort, split by who’s best placed to handle what. Neither of us could do this trip properly working from the other’s list.
None of it is glamorous. All of it is the difference between arriving ready and arriving hoping.
The bit nobody packs for
Something else happens in the final stretch before a big trip, and it has nothing to do with logistics.
You spend weeks looking forward to escaping the norm. The alarm, the inbox, the routine. Then somewhere in the last fortnight you start noticing the norm you’re about to leave, in slightly ridiculous ways. Who’s going to keep an eye on the garden. Whether you’ll miss the Saturday morning. And once you’ve actually arrived, more so again: three days into a trip you waited a year for, you find yourself thinking about your own kitchen.
Retirement does this on a scale that catches people completely off guard, and the last stretch before you stop is when it starts to surface.
The colleagues, first. Not the job, the people. The one you have coffee with who knows exactly what your week has been like without you having to explain it. A social network that came free with the building and largely disappears the day you hand your pass in.
The routine, which nobody admits to missing until it’s gone.
And the weekend. This is the one I hear most often, usually said half apologetically, as though it’s an odd thing to care about. A weekend only feels like a weekend because of the five days standing in front of it. Take those away and you have seven days in a row, which sounds like a gift right up until it’s Tuesday, it feels like Sunday, and you’ve no idea what to do with either.
A weekend only feels like a weekend because of the five days standing in front of it.
Worth asking, in the last stretch: how many weekends have you got left that are genuinely weekends?
None of that is a reason to stay. It’s a reason to know it’s coming, because the things you’ll miss are the things you’ll want to replace, and replacing them is a plan rather than a regret.
The bit that gets skipped
Here’s the parallel that matters.
Most people approaching retirement have paid the balance. Thirty years of pension contributions, a mortgage cleared or nearly, savings put by. The financial commitment has been made, often faithfully, over decades.
What almost nobody does is the last four weeks. The practical half: what does the first year actually look like, week by week, not the brochure version but the real one? What happens on a wet Tuesday in February when there’s nowhere to be? And the other half: what are you replacing, and who with?
That’s the preparation. In retirement it doesn’t get done, not because people are careless, but because nothing tells them it’s time to start.
Teachers get a deadline, and it still isn’t enough
If you want the clearest example of all this, look at teaching.
Teachers are one of the few groups who genuinely do get a deadline. Notice to leave at the end of the summer term usually has to be in by the end of May. A real date, a real cut-off, consequences for missing it. Almost exactly the balance-payment reminder the rest of us never receive.
And it still isn’t enough.
The notice goes in, the term finishes, and then it’s the summer holiday. Six weeks that feel precisely like every other summer has felt for thirty years. Same rhythm, same weather, same slow start. Nothing announces itself as different.
It’s September that does it. The first week of a new term that isn’t yours. No timetable, no classroom, nobody expecting you. That’s the week it becomes real, and by then the preparation window has already closed behind you.
Which makes the point better than I can. The deadline forced the decision. It did nothing whatsoever about the preparation.
The deadline forced the decision. It did nothing about the preparation.
It isn’t a character flaw. It’s a missing deadline
To be fair to retirement, it isn’t completely silent. The prompts are there, they’re just quiet and they arrive without instructions.
The pension statement that came in and went into the drawer unopened. A colleague’s leaving do, and the odd feeling on the drive home. A birthday with a nought on the end. A friend your age who’s had news you weren’t expecting.
Every one of those is a reminder. Not one comes with a date attached, and nothing bad happens if you ignore it, so it gets noticed, felt for a day or two, and filed.
I’ve written before, in the piece that opened this series, that people will spend longer planning a fortnight away than they ever spend planning thirty years of retirement. That sounds like an accusation and it really isn’t. The holiday gets planned because it has to be. Retirement has none of that machinery: the date is soft and endlessly moveable, and no envelope ever arrives.
It isn’t a character flaw. It’s a missing deadline.
Which means the fix isn’t more willpower. It’s building the deadline yourself.
Send yourself the reminder
Simpler than it sounds, and it takes an evening.
Pick a date. Not a decision, a date, and provisional is fine. The month and year you’d like to stop, or reduce, or change how you work. Write it down somewhere you’ll see it, because a date held loosely in your head isn’t a date, it’s a mood.
Then count backwards. For a holiday the real preparation window is about four weeks. For retirement it’s closer to twelve to eighteen months, and if you’re on a scheme with notice deadlines and fixed draw dates, longer still. Mark that point in the calendar. That’s your balance-payment reminder, and you’ve just sent it to yourself.
Make sure the date is genuinely yours, too. It’s remarkably easy to inherit a colleague’s timing without ever noticing, which is the trap I wrote about last month.
One more job, the smallest on the list. If there’s a pension statement in a drawer, open it. If you don’t have a State Pension forecast, get one. It takes about five minutes and it’s the cheapest piece of clarity available to anyone in this country.
If nobody’s going to send you the reminder, you’ll have to send it yourself.
The last few days
Our balance was paid in June. We travel in a matter of days, and the work that’s actually made us ready happened in the last four weeks, not the first eight. The reminder didn’t prepare us. It just told us to start.
Retirement gives you the same shape and none of the prompting.
So the question isn’t whether you’re saving enough, or whether the number is right, or what anyone else is doing.
It’s this: what’s your date, and who’s going to remind you?
If you’d like some help working that out, a discovery call costs nothing and there’s no agenda attached to it. Or if you’d rather just have a bit of this thinking arrive every couple of weeks, the newsletter is the easiest way in. I’m here when you’re ready.
Paul

